

Last time I wrote I put on some QQQ downside and this week I took off half and subsequently bought some QQQ calls as NQ approached 29k. NQ has managed to hold that 29k area well since May, there have been a few moves below it but each time has been met with a sharp rally back above it. I also covered half of the EUR/JPY short at 179 against the 184.1 entry, which moved so quickly that I had not even finished sizing it. MCD was cut for a small loss in the week.
I think Friday made it clear that positioning was too bearish going into CPI. It came in hotter than expected, and equities rallied while vol and skew got crushed. Simply put, too many people were too heavily hedged for a bad outcome, and a disappointing number was not enough to justify another leg down. You could see this positioning tale in Goldman’s prime data which showed investors adding shorts in macro products ahead of the release while buying individual TMT names.
When I talk about positioning, I am interested in what people have already done with their view. Someone who is worried about inflation who has already reduced exposure is in a different position from someone equally worried who remains fully invested, which matters when the number arrives. A bearish surprise does not necessarily trigger another wave of selling if enough people have already acted; many of those will be putting exposure back on when the market fails to fall.
I think a lot of the damage from higher rates is already priced in. One or two hikes by themselves wouldn’t make me bearish, particularly with more than three priced over the next year. Does the Fed actually hike in September? I am not sure, but the more attractive trade is rates being left where they are. I won’t pretend to have a way of knowing what’s going through every Fed member’s head, but I do have a view on how much tightening equities can tolerate. I think it could turn out to be less unpleasant than investors have been prepping for.
I think the big question here is what happens if some of the pressure starts to reverse. Obviously, energy is still the biggest concern in the inflation picture. If the fighting were to ease with Iran, you would see oil come off and inflation expectations move lower with it. From here, it may well be the catalyst that finally cracks the range index has been in for some time. I think that people spend so much time working out what the next disaster might be that their books are badly set if anything gets better.
Amid all the noise around rates, Iran and AI, people are spending too much time focusing on the market getting cheaper. By cheaper, I mean the index falling. This is a problem with hyper-focusing on price 24/7, they are yet to check their rear view mirror and notice that the multiple has already come down to 19x forward earnings. I guess it’s an easy thing to do when you’re waiting for a particular level on index to validate/invalidate your thesis. But part of the valuation adjustment you wanted has already happened, you were just too busy focusing on price. To be clear, I am not saying that 19x is some bargain, I am just saying that waiting for another big sell off might not be the right thing to do here. If equities were still getting more expensive going into potential hikes, I’d be a bit more worried.
Let’s get the big discussion out the way as I have received endless messages about it over the weekend and I can just answer here… Any follow up questions, feel free to message. So Dario Amodei… He basically says that he wants a slower pace of frontier development because he thinks capabilities are getting ahead of the work needed to keep them safe (this is bullish PANW + CRWD as shown with todays price action, both of these are in the Phase 3 basket). His note did make me think of Nick Bostrom’s book Superintelligence, worth a read if you haven’t. Taking longer to develop the next model doesn’t mean customers stop using what already works. I’d be more concerned if it delayed the capabilities they’re actually waiting to pay for.
What I could takeaway after reading feedback from Goldman’s Communacopia conference was strength. The biggest constraints were on meeting demand. Memory and storage commentary pointing to further tightness for another year to 18 months. What’s been awkward about this whole Amodei post is that after a positioning clear-up in AI, people had quite literally just started to put this trade back on. Me included, I just had doubled CRDO and I put on ASML last week at 10%. I think most of this morning’s dip was panic from this cohort, as it’s not really shaken me. And BTW, please don’t take my explanation of Friday’s session to mean that every bad headline will be bought because nobody owns anything, because that isn’t what positioning is saying at all, nor what I am saying. I can think the market was too heavily hedged for CPI without assuming that the names bought during conference season are now immune to an AI scare.
The AI capex data is getting more interesting again. I am pretty sure I have said a few times recently that capex continuing to increase without enough coming back would be a concern. So something worth looking at as a trade would be higher capex companies that have seen their stock fall even as their relative earnings have held up since those will already be on a lower multiple.
I could also see people welcoming companies slowing spending if the company keeps getting more revenue out of the capacity that it has already built, without constantly increasing capex. This could genuinely be a very bullish scenario as it’s different from capex and would give them time to sit back and figure out how much more capex is needed going forward.
Another popular topic over the weekend was Oracle… If anything this has been one of the most popular names discussed over the past twelve months. It remains one of my largest positions (and offside) so I thought I’d put a few thoughts down on paper following earnings as when I say spending needs to produce something, the same applies here too.
The latest quarter gave us a big acceleration in revenue from 11% growth a year ago to 30%. Cloud infrastructure grew 120% in constant currency and management expects that infrastructure growth rate to accelerate further through 2027. Meanwhile the FY27 capex guide stayed at 90-95B with capex still expected to peak in either FY27 or 28. I would say that’s a positive… Faster infra growth without another increase in capex is better than the main thing to be going up being capex.
What should stand out is the more than 30B of additional AI cloud contracts signed during the quarter. Oracle has said the way those contracts are structured means there is no incremental impact on its plans to raide capital. Though this leads me to what I always think about the company, I always am asking myself how much needs to be spent before the customer starts paying. Oracle reported 23B of operating cash flow against 28.5B in capex. For those asking, yes I am still bullish but I am left a lot of the time asking too many questions with this name and I don’t like holding names that make me do that.
We progress… onto another large holding. Meta… At least a bit more positive. Small anecdote but I will get to the point… Try thinking about a service that you keep renewing even though you’re fairly sure there’s a better deal elsewhere. You may spend an afternoon comparing everything and sorting out the move, but you have other things to do, so it ends up being left for another day. Now imagine being able to ask an agent to handle most of that. The company providing the service doesn’t have to disappear for its economics to change but it might have to compete harder for a customer it used to keep without having to do much. How much of the customer relationship is actually loyalty and how much is hassle?
This is the part of the current Meta discussion that interests me the most right now. RIP Muse btw, Zuck snatched their Instagram handle and gave them MuseBand. Muse is designed to do things for people like shopping, booking travel and tickets and so forth, rather than just giving you another answer in a chat window. It’s managed to get to 2nd in the US app store, which sure is encouraging, but it’s all about whether people will keep using it once they’ve finished trying it out.
If people trust an agent to do stuff for them, then the agent starts to have a say in where the money goes. Of course, people will need to build a lot of trust with it first. You may be happy letting agent find you a flight but not as happy letting it book the flight with your bank details. Meta has said that Muse will ask for approval before sensitive actions like paying, so you’re not just handing it the keys and hoping for the best. For the consumer, I would say that if it saves you an hour on admin while leaving you the final say in checkout, that would be a decent start no?
I just hope Muse isn’t the next Threads, which was a complete flop where people downloaded it because everyone was talking about it and then stopped after a few days. If this habit sticks and the economics work eventually, then I think there is considerably more to it than being another AI app on your phone…
Anyway, away from single names for a moment… On to positioning. Fundamental L/S Gross at 205% (14th %ile on a 1yr lookback, 63rd %ile on a 3yr) and net at 56.3% (61st %ile on a 1yr lookback and 73rd %ile on a 3yr). The gross number looks light compared to the past year, but the net is not particularly low. I am more interested in where people are choosing to put risk back on.

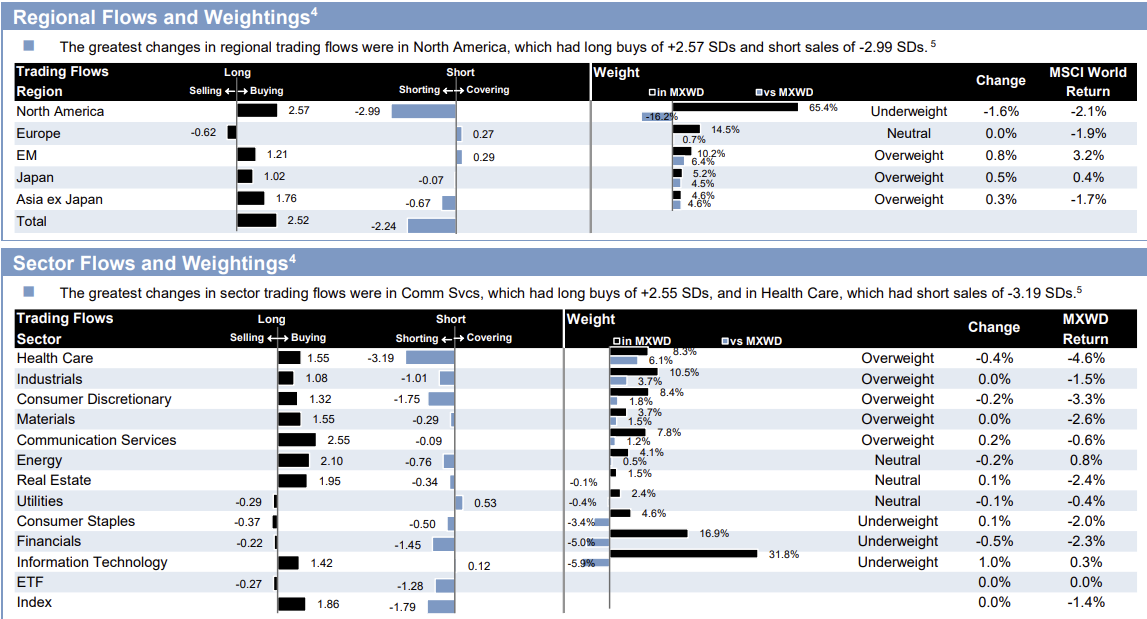
Which leads me back to my comment about people putting the AI trade back on… Goldman Prime had TMT as the most $ net bought global sector, with the net buying being the largest in seven months, driven almost entirely by long buys. Positioning is nowhere near as stretched as it was, and I’d put a lot of this risk being put back on due to people being back at their desks after a long boozy stretch in Europe this summer.
The pain trade remains up, and my fingers remain ready to pull the trigger. I have a few names that have gone onto the immediate watchlist. Nothing put on just yet, but they are the next ones I want to spend some time watching. I am not necessarily short of exposure, which is one of the reasons I sold MCD to make some room for fresh ideas.
AKAM SNPS KWEB DAL GTLB OKTA
The less-friendly bit is the systematic flow: CTAs sold ~15B in global equities last week but still have roughly 120B of net length, which is in the top quartile on a 1-year lookback. Estimates have another 20B of selling this week on a flat tape which is worth considering when trading tactically. A lot of that flow may have already happened to be fair with the overnight dip. The tell will be whether equities can hold up and absorb the supply.
The main thing that matters this week is the Fed and the reaction afterwards. I genuinely think that a hike could end up with a rally dependent on the presser. I mean Warsh wanted live meetings; he got it - the hike is basically priced in but not fully.
Another active week for me on tap… One final thing before I sign off. For anyone getting chopped up in this range, be careful about comparing your actual trading to what you could have made with the benefit of hindsight. Imaginary PnL can do a lot of damage and the temptation is to become more active until something starts working but in reality the best thing you can do is wait until you feel it’s right to re-engage. Take a step back and work out what exactly has stopped working; trade smaller and if trading options, extend the expiry a little.
250 likes and 150 restacks, and I’ll hand three of you a free annual sub.
Have a great week,
Fed
Good Morning. Thanks for another great article. I'm having trouble following your trades over the last month or so. I know there weren't many, and that's kind of the point, but I missed on when you bought those QQQ puts and those sure would've been helpful. Cheers!
Bond mkt is handing the Fed a free hike since it’s already there. One potential scenario is that the Fed does hike and Warsh is a bit more dovish in the presser to appease Trump.
Agree, the pain trade is up.